National News
GJEPC seeks government intervention over US reciprocal tariff proposal

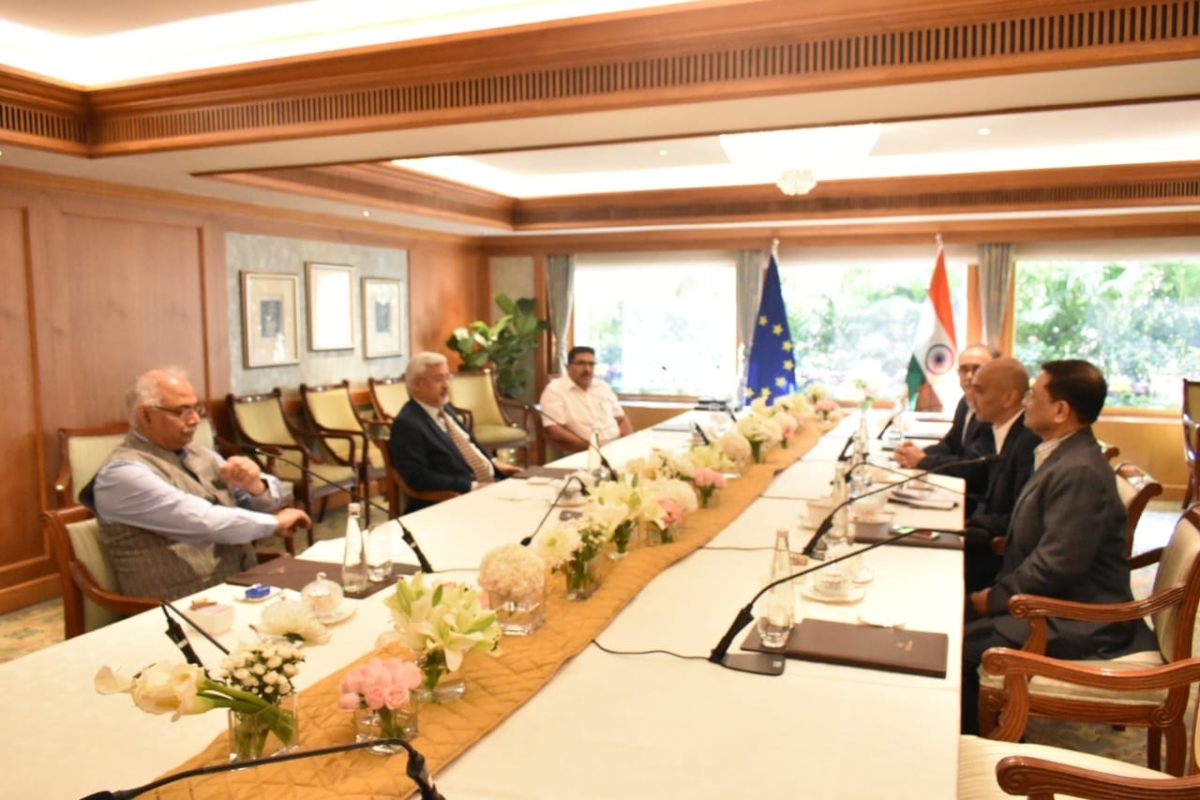
Top representatives of India’s gems and jewellery sector have urgently briefed Hon’ble Commerce Secretary Sunil Barthwal, IAS, on the potential repercussions of the United States’ recent notice regarding reciprocal tariffs. The delegation, led by Shaunak Parikh, Vice Chairman, GJEPC, along with Adil Kotwal, President, Seepz Gem & Jewellery Manufacturers’ Association (SGJMA), and Sabyasachi Ray, Executive Director, GJEPC, presented a detailed overview of the industry’s concerns and proposed mitigation strategies.
The briefing aimed to underscore the significant impact the proposed tariffs could have on Indian exports and the broader industry. Satya Srinivas, IRS, Additional Secretary, Ministry of Commerce (MoC), and Dnyaneshwar Patil, Development Commissioner, SEEPZ were also present to offer a comprehensive understanding of the issues at hand.
The US notice, which threatens reciprocal tariffs, has raised concerns within the Indian gems and jewellery sector, a key contributor to the nation’s export revenue. The industry leaders outlined the potential economic fallout and presented specific recommendations to safeguard interests.


National News
Gold loans surge: Borrowers pivot to secured credit on soaring gold prices
Driven by surging bullion prices, regulatory tightening on unsecured debt, and evolving consumer perceptions
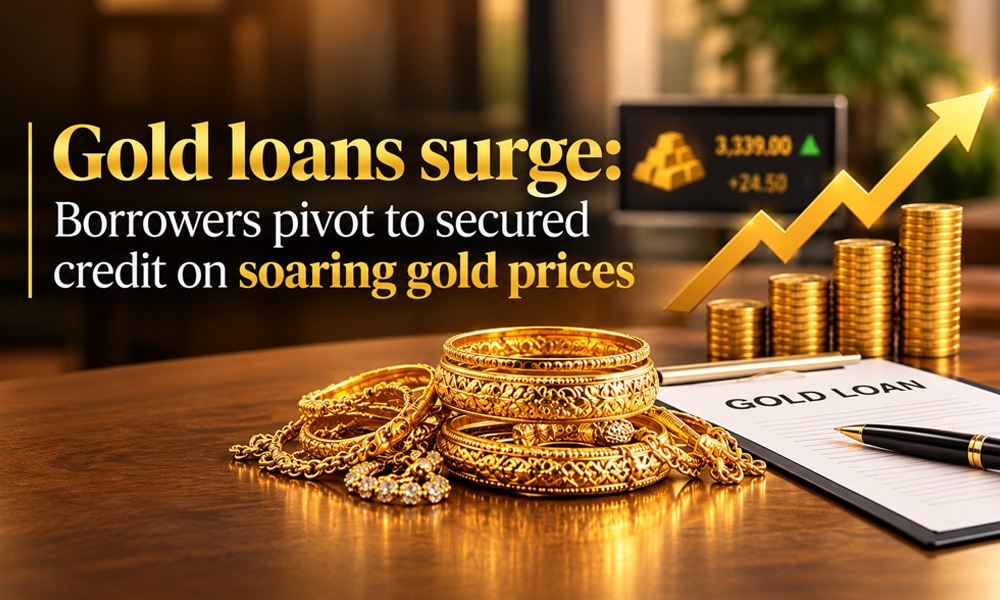
Driven by surging bullion prices, regulatory tightening on unsecured debt, and evolving consumer perceptions, gold loans in India are expanding at their fastest pace in years. Recent Reserve Bank of India (RBI) data shows bank loans against gold jewellery jumped 88.1% year-on-year (y-o-y) in July 2026, while Non-Banking Financial Companies (NBFCs) recorded a 68.5% y-o-y increase.
This trajectory significantly outpaces broader retail credit lines. In comparison, combined NBFC retail loans grew by 21.4% y-o-y, and overall bank personal loans expanded by just 16.2% over the same period.
Key Market Drivers Fueling the Boom
Soaring Collateral Value: Domestic gold prices nearly doubled from ₹74,152 per 10 grams in September 2024 to ₹1,51,687 by September 2026. This appreciation allows borrowers to secure higher loan values against the same physical gold. The average gold loan ticket size grew from roughly ₹1 lakh in FY24 to ₹1.7 lakh in FY26.
Tighter Regulatory Norms for Unsecured Credit: Following the RBI’s 2023 risk-weight hikes on consumer credit (raising weights from 100% to 125% for personal loans and up to 150% for NBFC credit cards), lenders shifted focus toward gold-backed collateral.
Higher Loan-to-Value (LTV) Caps: Under revised regulatory frameworks effective April 1, 2026, the RBI replaced the flat 75% LTV cap with a tiered structure, allowing up to 85% LTV for loans up to ₹2.5 lakh, enabling greater liquidity access for small-ticket borrowers.
Streamlined Origination & Lower Rates: Gold loans remain highly cost-effective, typically priced between 8.5% and mid-20% per annum compared to 10–30% for personal loans. Loans under ₹2.5 lakh require minimal documentation, bypassing formal income proof and mandatory credit checks.
Expanding Borrower Demographics
The gold loan portfolio outstanding reached ₹22.7 trillion in August 2026, accompanied by broadening demographic participation.
Data from CRIF India reveals expanding participation among women borrowers—who now account for 42.3% of the outstanding portfolio—alongside a rise in “low risk” credit profiles (increasing from 41% to 48.6%), indicating widespread adoption among financially stable households and younger borrowers viewing gold as an active financial instrument.
Advisory for Borrowers
Industry experts urge borrowers to exercise prudence despite easy accessibility:
Evaluate Total Costs: Beyond headline interest rates, assess processing fees, valuation charges, and renewal costs before committing.
Choose the Right Structure: Match earnings cycles to repayment modes—EMIs suit steady salary earners by reducing principal interest over time, whereas bullet payments suit lump-sum incomes but accrue higher cumulative interest.
Avoid Over-Leveraging: Borrowing at the maximum 85% LTV limit leaves no buffer against potential market price dips, which could prompt unexpected margin calls or additional collateral demands from lenders.


Gold loans surge: Borrowers pivot to secured credit on soaring gold prices

GJEPC India Pavilion at WJSME 2026 showcases India’s jewellery mfg.and design capabilities

Malabar Group Signs Letter Of Intent With The West Bengal Government To Strengthen CSR Partnerships and Advance Inclusive Development
Gold loans surge: Borrowers pivot to secured credit on soaring gold prices

Heer By GIVA Reimagines 9KT Gold For The Everyday With Anushka Sharma
GJEPC India Pavilion at WJSME 2026 showcases India’s jewellery mfg.and design capabilities
-
 National News2 hours ago
Gold loans surge: Borrowers pivot to secured credit on soaring gold prices
-
 BrandBuzz23 hours ago
Heer By GIVA Reimagines 9KT Gold For The Everyday With Anushka Sharma
-
 International News3 hours ago
GJEPC India Pavilion at WJSME 2026 showcases India’s jewellery mfg.and design capabilities
-
 National News21 hours ago
Malabar Group Signs Letter Of Intent With The West Bengal Government To Strengthen CSR Partnerships and Advance Inclusive Development