National News
GJEPC Delhi launches 3rd Batch of GJ Export Training Programme


GJEPC’s Northern Regional Office successfully launched the third batch of its training programme, “How to Start Exports of Gems and Jewellery.” Designed as a hybrid model, the programme offers one- and three-day sessions aimed at equipping aspiring exporters with practical insights into the export process.
The latest batch saw the participation of 13 students, with 6 attending online and 7 offline. Shri Antarpal Singh Sawhney, Regional Chairman (North), GJEPC, interacted personally with the participants, sharing industry experiences and motivating them to confidently embark on their export journeys.


National News
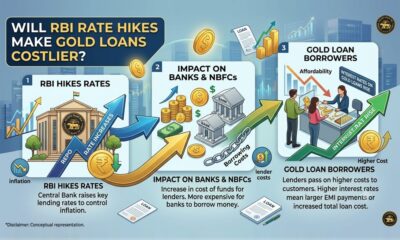
Will RBI Rate Hikes Make Gold Loans Costlier?
With Bullion rIces Sliding From Recent Peaks, Borrowers Face A Dual Squeeze: Potential Upward Adjustments On Floating Borrowing Costs and Lower Loan Amounts Against Pledged jJewellery.

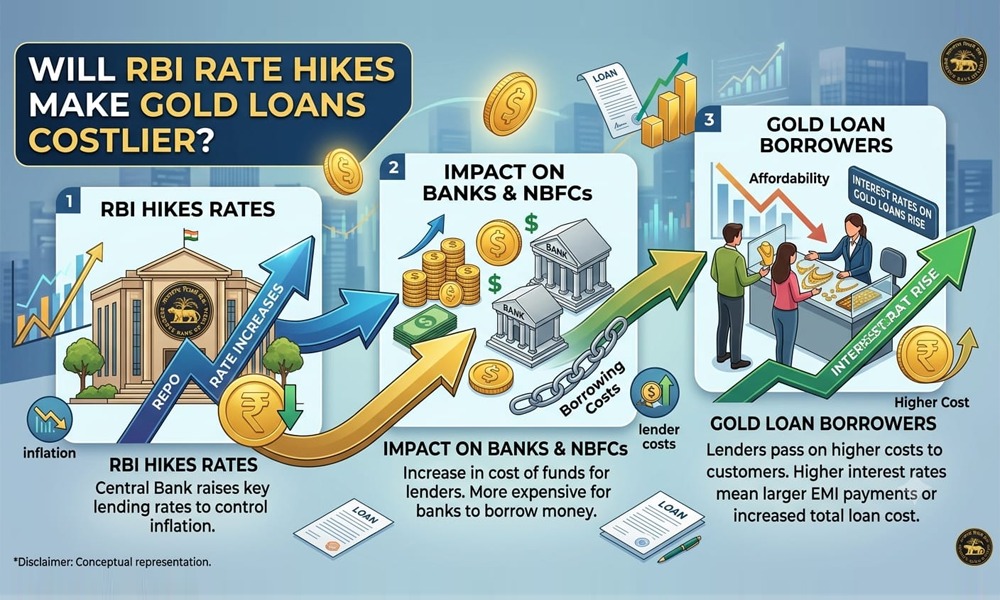
Potential rate hikes by the Reserve Bank of India (RBI) could push borrowing costs higher across the financial system, but the transmission to gold loans will not be immediate or uniform across all lenders, analysts and industry executives said. With bullion prices sliding from recent peaks, borrowers face a dual squeeze: potential upward adjustments on floating borrowing costs and lower loan amounts against pledged jewellery.
Key Takeaways for Borrowers & Lenders
Non-Uniform Transmission: A repo rate hike does not guarantee a 1:1 surge in gold loan rates. Lenders pricing credit via non-bank finance company (NBFC) cost-of-funds channels may adjust rates on a different timeline compared to banks operating direct floating-rate transmission models.
Loan Structure Matters: Existing fixed-rate borrowers remain protected for their contract term, while floating-rate borrowers face higher interest costs upon contract reset dates.
Collateral & LTV Risk: A fall in gold prices reduces the value of pledged collateral relative to total debt. Lenders are required under RBI regulations to enforce a strict loan-to-value (LTV) ceiling of 75%, leaving borrowers vulnerable to margin calls or mandatory partial pay-downs if market prices breach regulatory margins.
Commercial banks experience a high and direct immediate impact from a central bank rate hike, as their benchmark-linked External Benchmark Lending Rates (EBLR) force floating borrowing costs to reset quickly.
In contrast, gold loan NBFCs face a moderate or delayed impact, with interest rate adjustments depending on their broader liability structure, wholesale borrowing costs, and competitive market positioning.
For fixed-rate contracts, a rate hike has no immediate impact, keeping borrowing costs steady until the specified term ends. Conversely, floating-rate contracts carry a high impact, with interest charges stepping upward automatically on the loan’s next periodic reset date.
Strategic Considerations
Borrowers considering a gold loan amidst rate uncertainty and volatile commodity prices should evaluate the following structural factors:
Calculate Servicing Capacity: Assess whether monthly cash outflows can accommodate potential interest rate resets on floating-rate agreements.
Review LTV Margins: Evaluate pledged jewellery value at current spot rates to maintain a safety cushion above the mandatory 75% LTV regulatory threshold, mitigating auction risk during sharp gold pullbacks.
Compare Fine Print: Look past headline interest rates to evaluate reset frequencies, processing charges, prepayment penalties, and default auction clauses across competing bank and NBFC offerings.

-
 New Premises2 hours ago
Palmonas Expands UAE Presence With New Retail Outlet At Mall Of The Emirates
-
 International News2 hours ago
Jewelers International Showcase Fall 2026 Returns To Miami Beach This October
-
 National News2 hours ago
Will RBI Rate Hikes Make Gold Loans Costlier?
-
 National News4 hours ago
GJEPC Holds 60th AGM, Reviews FY2025-26 Performance and Industry Priorities