National News
Raniwala 1881 Partners with Francorp to Scale Retail Footprint Through Franchising
The iconic Jaipur-based jewellery house adopts FOFO and FOCO models to expand across India while preserving its royal heritage and artisanal legacy

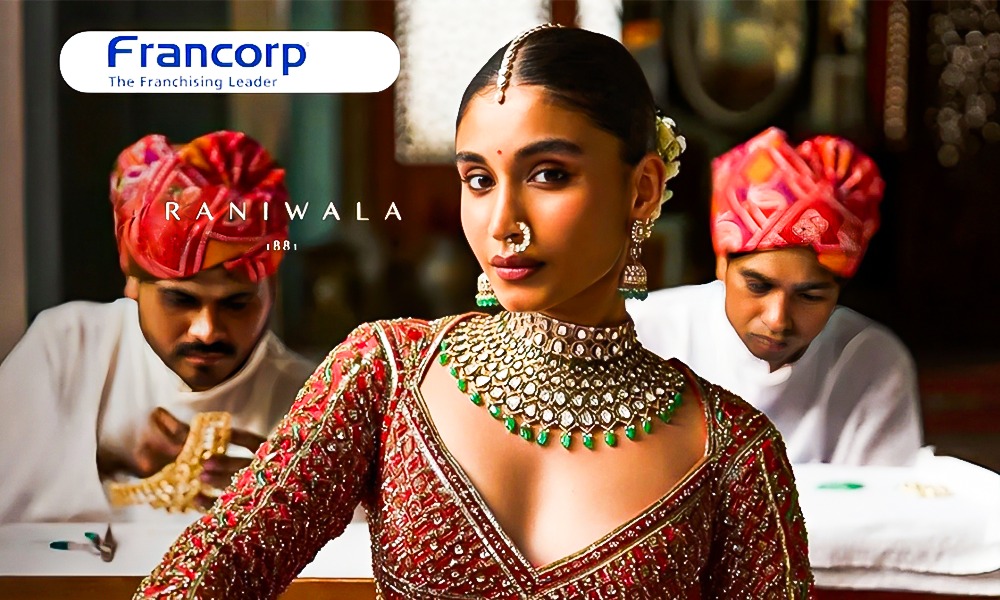
Raniwala 1881, the luxury jewellery brand rooted in Jaipur’s rich heritage, has announced a strategic alliance with Francorp, the franchising advisory arm of Franchise India Group, to fuel its next phase of growth through a structured franchise model.
This partnership marks a significant milestone for the 140-year-old brand as it seeks to expand its retail footprint across India while staying true to its legacy of regal design and meticulous craftsmanship.
Under the agreement, Raniwala 1881 will implement both Franchise-Owned, Franchise-Operated (FOFO) and Franchise-Owned, Company-Operated (FOCO) models. These formats aim to offer opportunities for entrepreneurs and investors to be part of the evolution of one of India’s most prestigious fine jewellery brands.
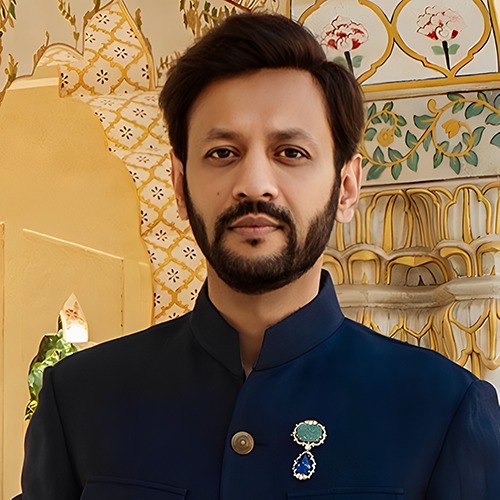
“Our jewellery is more than just adornment; it is a representation of centuries-old craftsmanship and a deep-rooted heritage,” said Abhishek Raniwala, Managing Director of Raniwala 1881. “With the growing demand for handcrafted Polki and Jadau jewellery, this partnership with Francorp allows us to expand while preserving our brand’s exclusivity.”
Founded in the 19th century by Rai Bahadur Champalal of Beawar, the brand carries a legacy dating back to the British era, when the family was honored with the title “Raniwala.” The brand continues to be a trusted name in bridal jewellery, known for its 18-karat gold Polki pieces that appeal to both Gen Z and Millennial audiences.
Over the years, Raniwala 1881 has also collaborated with some of India’s top fashion designers, including Sabyasachi Mukherjee, Manish Malhotra, and Rahul Mishra, reinforcing its place at the intersection of heritage and high fashion.
The shift toward franchising comes as India’s jewellery market undergoes a transformation, with consumers increasingly gravitating toward branded, story-driven luxury pieces that offer authenticity and traceability.
Francorp will help guide Raniwala 1881’s expansion across metro cities and fast-growing luxury markets, ensuring a consistent retail experience that honors the brand’s heritage.

“Luxury retail is evolving rapidly, and heritage brands like Raniwala 1881 are leading the way in strategic expansion while maintaining timeless elegance and exclusivity,” said Gaurav Marya, Chairman of Franchise India Group. “Franchising provides an effective model to scale without compromising brand integrity. With FOFO and FOCO formats, we’re introducing a new dimension to luxury jewellery retail in India.”



National News
Will RBI Rate Hikes Make Gold Loans Costlier?
With Bullion rIces Sliding From Recent Peaks, Borrowers Face A Dual Squeeze: Potential Upward Adjustments On Floating Borrowing Costs and Lower Loan Amounts Against Pledged jJewellery.

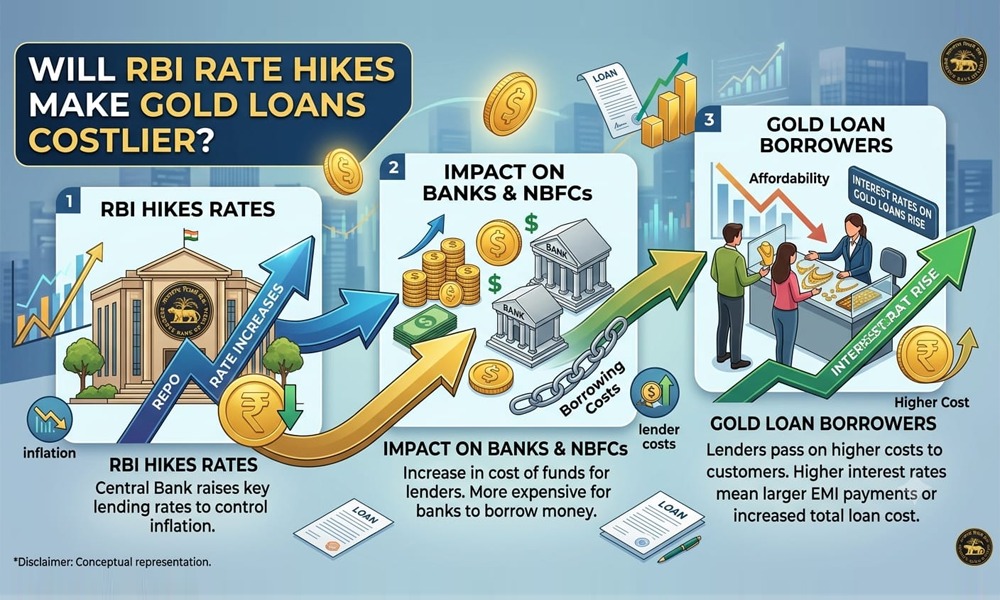
Potential rate hikes by the Reserve Bank of India (RBI) could push borrowing costs higher across the financial system, but the transmission to gold loans will not be immediate or uniform across all lenders, analysts and industry executives said. With bullion prices sliding from recent peaks, borrowers face a dual squeeze: potential upward adjustments on floating borrowing costs and lower loan amounts against pledged jewellery.
Key Takeaways for Borrowers & Lenders
Non-Uniform Transmission: A repo rate hike does not guarantee a 1:1 surge in gold loan rates. Lenders pricing credit via non-bank finance company (NBFC) cost-of-funds channels may adjust rates on a different timeline compared to banks operating direct floating-rate transmission models.
Loan Structure Matters: Existing fixed-rate borrowers remain protected for their contract term, while floating-rate borrowers face higher interest costs upon contract reset dates.
Collateral & LTV Risk: A fall in gold prices reduces the value of pledged collateral relative to total debt. Lenders are required under RBI regulations to enforce a strict loan-to-value (LTV) ceiling of 75%, leaving borrowers vulnerable to margin calls or mandatory partial pay-downs if market prices breach regulatory margins.
Commercial banks experience a high and direct immediate impact from a central bank rate hike, as their benchmark-linked External Benchmark Lending Rates (EBLR) force floating borrowing costs to reset quickly.
In contrast, gold loan NBFCs face a moderate or delayed impact, with interest rate adjustments depending on their broader liability structure, wholesale borrowing costs, and competitive market positioning.
For fixed-rate contracts, a rate hike has no immediate impact, keeping borrowing costs steady until the specified term ends. Conversely, floating-rate contracts carry a high impact, with interest charges stepping upward automatically on the loan’s next periodic reset date.
Strategic Considerations
Borrowers considering a gold loan amidst rate uncertainty and volatile commodity prices should evaluate the following structural factors:
Calculate Servicing Capacity: Assess whether monthly cash outflows can accommodate potential interest rate resets on floating-rate agreements.
Review LTV Margins: Evaluate pledged jewellery value at current spot rates to maintain a safety cushion above the mandatory 75% LTV regulatory threshold, mitigating auction risk during sharp gold pullbacks.
Compare Fine Print: Look past headline interest rates to evaluate reset frequencies, processing charges, prepayment penalties, and default auction clauses across competing bank and NBFC offerings.

-
 New Premises2 hours ago
Palmonas Expands UAE Presence With New Retail Outlet At Mall Of The Emirates
-
 International News2 hours ago
Jewelers International Showcase Fall 2026 Returns To Miami Beach This October
-
 National News2 hours ago
Will RBI Rate Hikes Make Gold Loans Costlier?
-
 National News5 hours ago
GJEPC Holds 60th AGM, Reviews FY2025-26 Performance and Industry Priorities