International News
Jewellery sector’s growth will be fueled by a younger, diverse clientele: McKinsey & Co luxury fashion report
Jewellery sales are expected to regain momentum with 3% to 5% projected growth. An increasing number of consumers will transition from non-branded to branded jewellery.


A 2025 luxury fashion report by McKinsey & Co forecasts jewellery and leather goods to be the fastest-growing categories of the luxury goods industry through 2027. The jewellery sector’s growth will be fuelled by a younger and more diverse clientele.
The report notes that in the period 2019-2023, the jewellery category experienced a remarkable 8% CAGR (compound annual growth rate), globally. However, in 2024, growth slowed down between 2% to 4%. This year, jewellery sales are expected to regain momentum with 3% to 5% projected growth, and accelerate to 4% to 6% by 2027.
Jewellery sector’s growth in the next 3 years will be shaped by shifting customer profiles and buying behaviours. An increasing number of consumers will transition from non-branded to branded jewellery.
High jewellery sales are likely to increase in line with the growing number of ultra-high-net-worth individuals worldwide. Moreover, growing interest among younger buyers in genderless jewellery, along with luxury brands investing in technology and immersive experiences will further shape interest among digital natives and new consumers
However, the report cautions that an uncertainty in a clear segregation between lab-grown diamond and natural diamond markets could pose a challenge to this growth.
Key points:
- Jewellery to grow globally between 4%-6% through 2027: McKinsey & Co.
- High-jewellery demand to rise as the wealthy population grows worldwide.
- Global iconic jewellery brands continue to lead growth for luxury conglomerates
- Diamond-studded jewellery to see the biggest growth in India in 2025: Redseer
- India’s precious jewellery market to grow at a healthy 11-13% CAGR until 2028
- Organised jewellery sector in India to grow 20% year-on-year in FY25: Ind-Ra



International News
The London Bullion Market Association Releases Country of Origin (CoO) Sourcing Report
Data Highlights Overall Stability In Gold Sourcing, A Slight Contraction In Silver Volumes

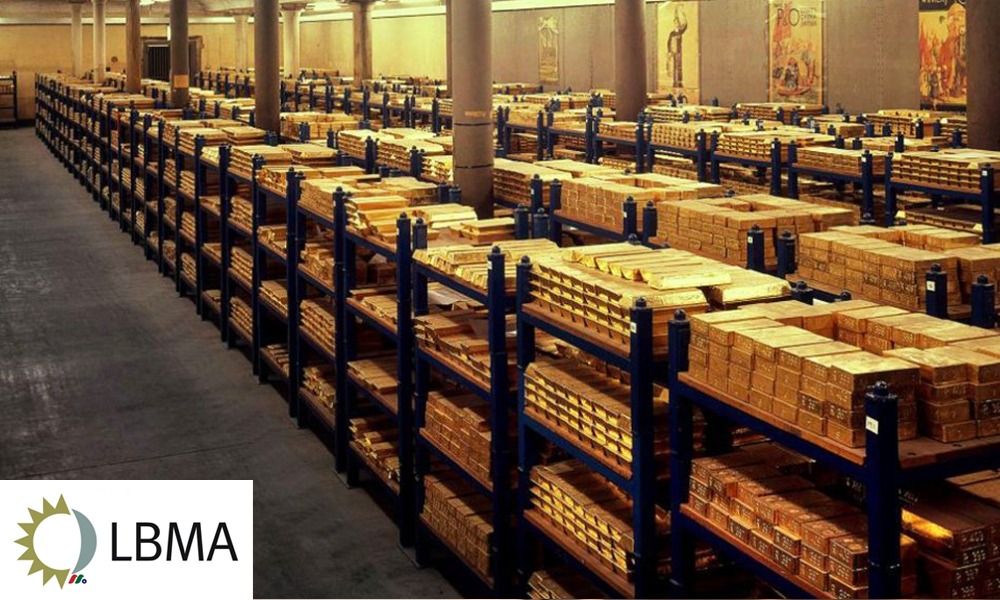
The London Bullion Market Association (LBMA) released its latest seven-year Country of Origin (CoO) sourcing report for Good Delivery List (GDL) refiners. The data highlights overall stability in gold sourcing, a slight contraction in silver volumes, and a continued dominance of recycled material across both metals.
Key Data Highlights
Gold Sourcing (5,536 tonnes total | ▲ 3% YoY)
Recycled Gold: Rose 7% to 3,755 tonnes, making up the bulk of overall supply.
Mined Gold: Dropped 5% to 1,782 tonnes.
Artisanal & Small-Scale Mining (ASM): Rose 24% to 54.6 tonnes (led by Bolivia at 18 t, Peru at 16 t, and the Philippines at 8 t).
Note
LBMA captures only a fraction of total global ASM production, estimated by Metals Focus at ~845 tonnes.
Silver Sourcing (33,446 tonnes total | ▼ 3% YoY)
Recycled Silver: 18,885 tonnes; Mined Silver: 14,561 tonnes
Notable Country-Level Trends
China: Gold recycling surged by 190 tonnes to reach 908 tonnes. In silver, reported mining volume spiked to 5,272 tonnes (up 2,212 tonnes), contrasting with independent estimates showing a modest national mine output drop.
Switzerland: Maintained its status as the largest European source for gold, accounting for 743 tonnes.


GJEPC Unveils India Pavilion At Doha Jewellery & Watches Exhibition

The London Bullion Market Association Releases Country of Origin (CoO) Sourcing Report

Unscrupulous Hallmarking Centers Are Compromising Purity Of Gold

IAGES Brings Together Accredited Gold Industry Stakeholders At Trust Circle 2026
The London Bullion Market Association Releases Country of Origin (CoO) Sourcing Report
GJEPC Unveils India Pavilion At Doha Jewellery & Watches Exhibition
-
 National News19 hours ago
IAGES Brings Together Accredited Gold Industry Stakeholders At Trust Circle 2026
-
 International News46 minutes ago
The London Bullion Market Association Releases Country of Origin (CoO) Sourcing Report
-
 National News39 minutes ago
GJEPC Unveils India Pavilion At Doha Jewellery & Watches Exhibition
-
 National News1 hour ago
Heavy Taxes Drive Cash Gold Sales Surge