JB Insights
Gold, silver retreat as volatility overrides dovish signals
By Gnanasekar Thiagarajan

Gold and silver ended lower on the week despite sharp intraday rebounds, with price action reflecting continued volatility and fragile positioning rather than a sustained recovery. In the absence of a definitive macro catalyst, a broad-based decline across equities and cryptocurrencies prompted investors to raise liquidity, briefly dragging gold below the key $5,000 per ounce threshold. Non-yielding assets came under pressure as earlier stronger-than-expected US employment data pushed expectations for the first Federal Reserve rate cut further into midyear, reducing the appeal of bullion. Sentiment shifted, however, after inflation data showed annual CPI slowing to 2.4% and core inflation easing to 2.5%, reviving dovish expectations. The softer inflation print weighed on Treasury yields and pressured the dollar, allowing gold to recover toward the $4,990 region. Silver experienced similar turbulence, sliding sharply during the liquidation phase before rebounding above $76 per ounce, though it remained on track for another weekly decline.
Gnanasekar Thiagarajan
Introduction:
Gold finished the period under pressure despite sharp rebounds, with price action dominated by cross-asset volatility and shifting rate expectations. After initially recovering more than 2% on softer-than-expected US inflation, bullion briefly pushed back toward the $5,000–$5,020 region as annual CPI slowed to 2.4% and core inflation eased to 2.5%, reinforcing expectations of multiple Federal Reserve rate cuts this year. Lower yields and a softer dollar provided near-term relief, reviving the structural appeal of non-yielding assets.
However, gains proved fragile as the dollar rebounded and gold slipped back below $5,020, underscoring hesitation around the psychological $5,000 threshold. Earlier strength in US labor data had already delayed expectations for the first rate cut toward midyear, capping upside momentum. Markets now await further guidance from FOMC minutes, GDP data and the core PCE print, while geopolitical developments — including renewed US-Iran nuclear talks and broader Middle East tensions — continue to shape safe-haven flows.
Silver tracked gold’s volatility but continued to underperform structurally, remaining in a corrective phase after January’s extreme surge. The metal rebounded nearly 3% on softer inflation data and firmer rate-cut expectations, briefly moving back above $76 per ounce, but gains faded as liquidity stayed thin amid China holidays and broader risk sentiment remained fragile. Heavy speculative positioning left silver exposed to sharp reversals, and prices are still far below late-January highs above $120 after the collapse toward the mid-$60s. While lower yields and debasement concerns offer underlying support, near-term trade points to consolidation rather than a swift return to the prior rally.
Gold and Silver:
Gold fell below $5,020 per ounce on Monday after rising more than 2% in the previous session, following weaker-than-expected US CPI data. The soft inflation print reinforced expectations for Federal Reserve rate cuts this year, with markets now pricing in slightly more than two reductions. Investors are awaiting the release of FOMC meeting minutes, the US GDP advance estimate, and PCE inflation data for further clues on the timing of the next rate cut. On the geopolitical front, traders are monitoring nuclear talks between the US and Iran, as well as US-led negotiations aimed at ending the war in Ukraine, both scheduled to resume on Tuesday. Developments in these areas could influence risk sentiment and safe-haven demand. Despite recent volatility, the precious metal remained supported by ongoing geopolitical uncertainty, strong central bank buying, and investor flight from sovereign bonds and currencies.
Silver March
Silver fell more than 1% toward $76 per ounce on Monday, reversing gains from the previous session, although trading volumes were subdued due to market holidays in the US, China and other countries. On Friday, the metal had jumped nearly 3% after soft US inflation data reinforced expectations that the Federal Reserve will cut interest rates later this year. Markets are currently pricing in a Fed rate cut in July, with a strong probability of a move in June. Investors now turn to the latest Fed minutes and the Fed-preferred core PCE price index report for further guidance on the US monetary outlook.
Meanwhile, mainland China’s markets are closed this week for the Lunar New Year holiday. Chinese traders had driven a speculative surge in precious metals in recent weeks, prompting authorities to curb market risks through various measures. Silver peaked above $120 an ounce in late January before falling to around $64 earlier this month as sentiment reversed.
Gold April
Technical View: $4996. Weekly chart shows a strong underlying uptrend with price holding well above the short-term moving averages and momentum expanding positively. The recent pullback appears corrective, with support seen near $4886/4878; holding above this zone keeps the broader structure intact for a move towards $5460. A decisive break below $4765 will be the first sign of deeper corrective pressure.
JB Insights
US Holiday Sales Will See 5.5% Growth For 2026 : Mastercard Economics Institute
This Resilience Reflects A Robust Labor Market, Rising Household Wealth, and Broad-Based Consumer Demand Across Income Cohorts. Overall, The 2026 Holiday Season Showcases An Adaptable U.S. Consumer Using Digital and AI Tools To Maximize Value While Continuing To Drive Broader Economic Momentum.

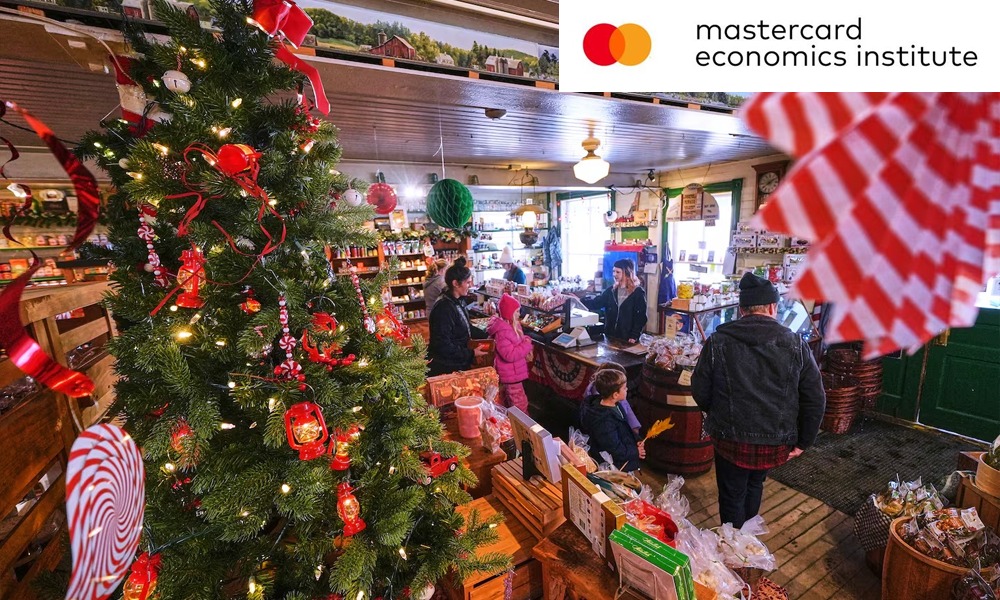
The Mastercard Economics Institute (MEI) forecasts a strong 2026 U.S. holiday shopping season (November 1–December 24), projecting retail sales excluding gas and autos to grow 5.5% year-over-year (YoY). This resilience reflects a robust labor market, rising household wealth, and broad-based consumer demand across income cohorts.
Key Drivers and Growth Channels
- Channel Performance: E-commerce continues to lead with an expected 11% YoY growth, but in-store sales are set to grow 3.6%—their strongest pace since 2022. This highlights the critical role of omnichannel strategies.
- Inflation Dynamics: Inflation accounts for 2.8 percentage points of the total 5.5% growth. Unlike last year’s tariff pressures, current price increases are driven by elevated energy/diesel costs and the massive AI infrastructure buildout.
- Calendar Shifts: A late Thanksgiving compresses the shopping window, pushing retailers toward early promotions. Additionally, Cyber Monday falling in November will shift significant online volume into the month.
The Role of Artificial Intelligence
AI is reshaping both prices and consumer behavior:
- Tech Inflation: High demand for memory chips and data infrastructure components has driven a 12.2% YoY increase in prices for info-processing equipment. Consequently, the consumer electronics category is projected to post outsized nominal sales growth (+10.7% YoY).
- AI Power Users: Consumers with paid AI subscriptions demonstrate distinct “optimization” habits. Data shows these users plan early, shop across a wider variety of boutique and specialty merchants, and aggressively target promotions during Thanksgiving weekend before transitioning to experience and hospitality spending in December.
Last-Minute Shopping Behavior
The final rush to Christmas offers key operational insights for retailers:
- In-Person and Malls: The final week before Christmas sees heavy physical store foot traffic, especially in enclosed shopping malls where consumers can complete multi-category purchases. Climate also plays a role: warmer-state residents (e.g., Florida, Nevada) are far more likely to make last-minute in-store runs than those in colder states.
- Transaction Value Trends: Average order values for children’s items peak near Black Friday, while premium categories—such as jewelry, cosmetics, luxury handbags, and department stores—see transaction values climb steadily from December 15, peaking on Christmas Eve as procrastinating shoppers pay a premium for convenience.
AI tools lower search costs for consumers, making price transparency higher than ever. Retailers must capture early November demand through targeted promotions before comparison tools push shoppers toward alternative or boutique brands.
Last-minute shoppers are price-inelastic and seeking speed. Malls and physical stores should maximize inventory for high-margin, rush-gift items (jewelry, cosmetics, designer goods, gift cards) in the final 10 days, leveraging store availability over promotional discounting.
Overall, the 2026 holiday season showcases an adaptable U.S. consumer using digital and AI tools to maximize value while continuing to drive broader economic momentum.


Kangana Ranaut Unveils PNG Jewellers New Showroom In Ayodhya~

GGJS 2026 Concludes With High-Volume Trade and Strategic Focus On Next-Gen Leadership

The Solitaire Festival Of India Concludes; Bumper Prize Winner At Ranka Jewellers Wins XUV 7XO
GGJS 2026 Concludes With High-Volume Trade and Strategic Focus On Next-Gen Leadership

ABARAN Commemorates The 125th Birth Anniversary Of Founder Shri Burde Sadananda Kamath With Special Gold Coin Launch

MCX Gold Silver Futures See Dip
-
 National News3 hours ago
GGJS 2026 Concludes With High-Volume Trade and Strategic Focus On Next-Gen Leadership
-
 National News8 hours ago
ABARAN Commemorates The 125th Birth Anniversary Of Founder Shri Burde Sadananda Kamath With Special Gold Coin Launch
-
 National News8 hours ago
MCX Gold Silver Futures See Dip
-
 National News3 days ago
P N Gadgil Jewellers Limited – Quarterly Update Q2FY27