International News
US Jewellery Retailers brace for a season of purpose

The diamond and jewellery industry steps into the November festive season with tempered optimism, facing a market characterized by a blend of aspiration and caution. While high-end and value-driven retailers see opportunity, middle-market brands brace for slower movement as consumers, particularly in the U.S., shift from impulse buying to mindful, purposeful spending.
Economic Headwinds and the Discount Demand
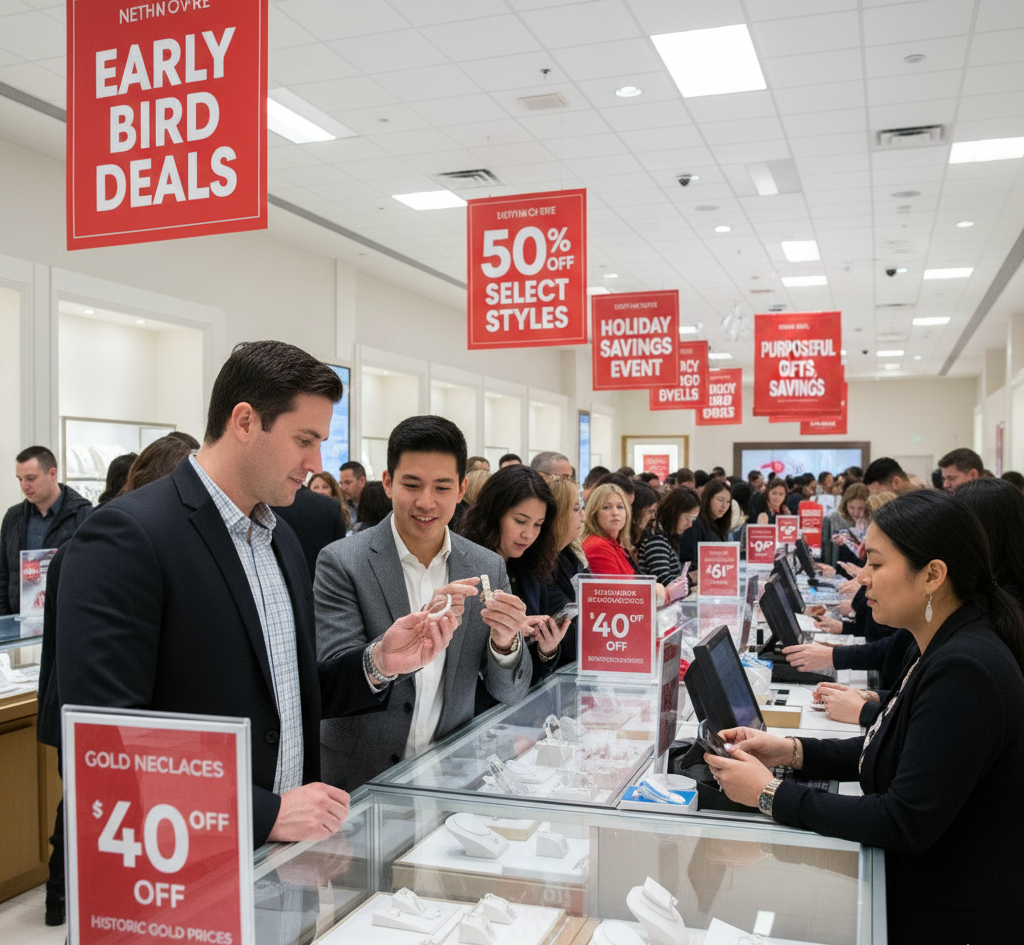
Economic uncertainty and rising costs are shaping consumer behavior. The National Retail Federation (NRF) reports that Americans plan to spend slightly less this holiday season ($890.49 vs. $901.99 last year), signaling a clear trend toward conscious buying. This cautious approach is compounded by historic gold prices and rising tariffs, which lead 85% of consumers to expect higher prices. Consequently, a “purposeful gifting season” is emerging, driven by a strong consumer desire for promotions and early-bird discounts.
Gen Z and the Shift to Values
Despite an overall consumer plan to delay non-essential purchases, jewellery remains an area of intended indulgence, notably led by Gen Z. Twenty-eight percent of Gen Z shoppers plan to spend on jewellery, outpacing all other generations. This influential demographic is fundamentally reshaping the market by demanding more than just sparkle; they prioritize quality, craftsmanship, and ethical integrity. Studies show 71% of Gen Z buyers focus on quality, while 39% are motivated by sustainability and responsible sourcing.
Redefining the Emotional Investment
This value-driven mindset is also prominent in the bridal segment. Younger couples view the engagement ring as a shared emotional investment, not a surprise. Key factors are quality (96%), customization (76%), and sustainability (88% of Gen Z). To manage budgets (average spend is $\$4,000-\$6,000$), many are embracing lab-grown diamonds for value. Current design trends favor refined simplicity: clean, minimal solitaires with elongated cuts (oval, cushion, marquise) in yellow gold, signaling individuality over overt opulence.
Luxury’s Steadfast Appeal
In stark contrast, the luxury market remains resilient. Its affluent clientele is driven by distinction, not discounts, fueling demand for rare stones and heritage craftsmanship. Major luxury groups report stable growth, supported by consumers who view jewellery as both an emotional keepsake and a tangible investment amidst geopolitical uncertainty. For this segment, bespoke creations, limited editions, and provenance-driven storytelling deepen the jewellery’s allure as a long-term asset.
The Common Thread: Authenticity
Ultimately, the 2025 festive season presents two distinct markets—value-driven shoppers seeking meaning and affordability, and affluent collectors seeking artistry and emotional depth. Both are converging on one central demand: authenticity. Whether through ethical sourcing, craft revival, or transparent storytelling, brands across all price points are realizing that modern consumers crave connection and substance as much as they crave beauty. The season’s sparkle is now undeniably rooted in substance.
International News
US Jewellery Companies Continued To Shrink In The Third Quarter:JBT
During Q3, Business Closures Dropped To 116 Compared To 126 In The Prior Year’s Third Quarter, Driven By 88 General Operational Cessations, 28 Acquisitions Or Mergers, and Zero Bankruptcies.

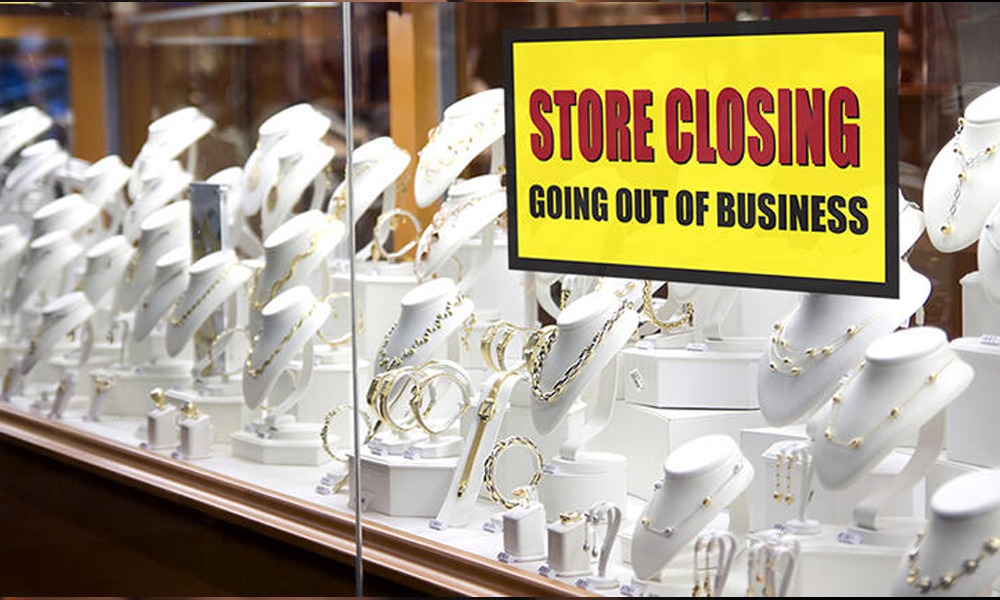
The number of active US jewelry companies continued to shrink in the third quarter, but at a slower pace than a year ago, according to the latest data from the Jewelers Board of Trade (JBT).The US jewelry industry continued its structural consolidation through Q3, though the pace of business closures showed signs of stabilizing compared to the previous year. Data from the Jewelers Board of Trade (JBT) reflects ongoing consolidation across retail, wholesale, and manufacturing, coupled with heightened credit volatility.
Key Data & Metrics
Nationwide, the active business footprint stands at 21,831 companies, reflecting a 1.4% year-over-year decline. During Q3, business closures dropped to 116 compared to 126 in the prior year’s third quarter, driven by 88 general operational cessations, 28 acquisitions or mergers, and zero bankruptcies. Meanwhile, new market entrants also slowed, with 67 new business openings recorded in Q3 down from 89 during the same period last year.
Sector-by-Sector Breakdown
| Sector | Active Count | YoY Change | Impact Summary |
| Retailers | 16,564 | -1.5% | Makes up the majority of the sector; experienced the largest net store count reduction. |
| Manufacturers | 2,061 | -1.7% | Steepest percentage decline among all segments. |
| Wholesalers | 3,206 | -0.9% | Relatively stable, holding the mildest contraction rate. |
Credit & Financial Health Trends
The JBT report highlights dynamic shifts in creditworthiness across US and Canadian businesses, signaling bifurcated financial health:
- Credit Downgrades: Jumped sharply to 1,655 (up from 620 in Q3 of the prior year).
- Credit Upgrades: Rose significantly to 1,480 (up from 551 in Q3 of the prior year).
While net business closures are tapering off, high numbers of simultaneous upgrades and downgrades point to a split market where resilient operators are strengthening their positions while vulnerable businesses face tighter financial pressures.


Aspect Bullion & Refinery Unveils Signature Collection At Two-Day Launch Event At Oberoi Mall, Mumbai

This Diwali, Say It With A Candere: Thoughtful Gifting Picks From Candere By Kalyan

Gold Is Back On The Moodboard: Palmonas’ 9KT Jewellery Picks For Festive Gifting

Dhanteras Shopping Guide 2026:Gold, Silver, Diamonds & Festive Jewellery Trends To Watch

The Solenne Collection: A Celebration Of Diwali By Bharti Bangur Fine Jewels

From Diya Puja To Diwali Soirées: Jewellery Designed To Go Beyond The Festive Season
-
 JB Insights1 week ago
Dhanteras Shopping Guide 2026:Gold, Silver, Diamonds & Festive Jewellery Trends To Watch
-
 BrandBuzz1 week ago
The Solenne Collection: A Celebration Of Diwali By Bharti Bangur Fine Jewels
-
 BrandBuzz1 week ago
From Diya Puja To Diwali Soirées: Jewellery Designed To Go Beyond The Festive Season
-
 National News1 week ago
Indriya, Aditya Birla Jewellery Unveiled India’s Largest Sustainable Jewellery Rangavalli