National News
Heavy Taxes Drive Cash Gold Sales Surge
Heavy Taxes On Official Purchases—A 15% Import Tax Plus A 3% GST Tax Make, Buying Gold Legally Comes With A Massive Extra Cost

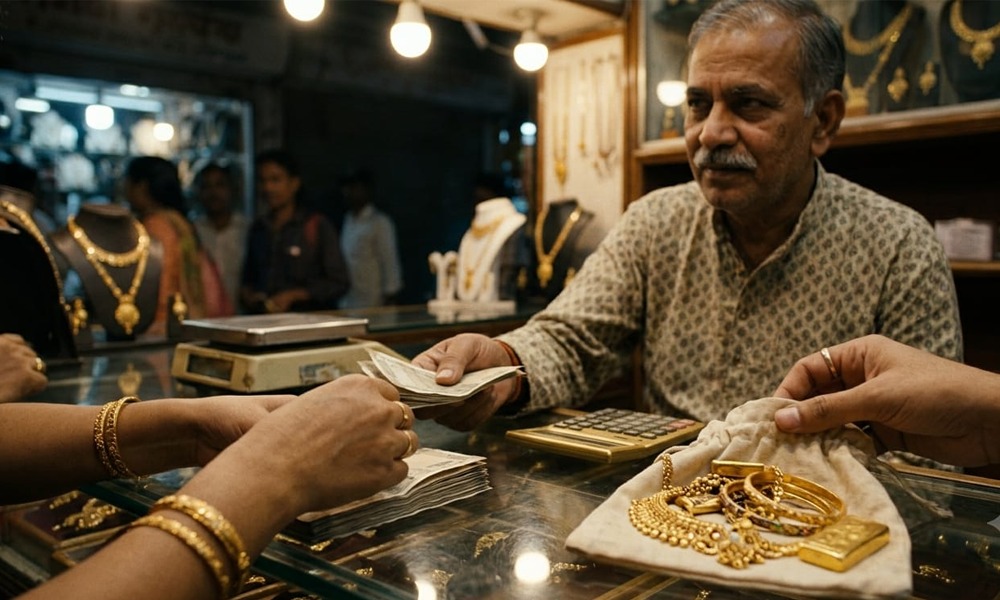
Gold prices have shot through the roof (nearly 30% higher than last year), and the government charges heavy taxes on official purchases—a 15% import tax plus a 3% GST tax. Because of this, buying gold legally comes with a massive extra cost.
Cash deals mean huge discounts
To avoid these high taxes, many local jewelers and buyers are skipping the paperwork entirely. Buying gold with cash off-the-books means no official receipts and no paper trail.
For regular shoppers: People buying wedding jewelry can save anywhere from Rs 5,000 to Rs 10,000 for every 10 grams just by paying cash without a bill.
For big buyers & traders: Bulk shoppers can save up to 6% off normal market prices. Unofficial suppliers are even managing to snag gold at discounts up to $200 an ounce—dwarfing the typical $50 discount seen through legal channels. As industry experts note, when import taxes are this high, it creates a massive incentive for gold to sneak past official channels.
Government rules backfired
The government raised taxes on gold to discourage people from buying imported metal, trying to keep money inside the country. Instead, it pushed the market underground. When taxes were low (around 6%), people didn’t mind paying legally. Now that taxes are at 18% total, dodging them is too tempting to pass up.
The timing couldn’t be worse
India’s massive wedding and festival season runs from mid-October to March, which is when gold buying spikes. With gold being a mandatory part of gifts and savings for Indian families, shoppers are prioritizing savings over receipts—making the illegal cash trade boom like never before
National News
FGLOC to host inaugural Gold Summit in Kochi
Will bring together key industry stakeholders to chart the future roadmap for the gold-loan sector and unlock the potential of gold as a financial asset

The Federation of Gold Loan Companies (FGLOC) will host its inaugural Gold Summit in Kochi on November 17, 2026, bringing together key industry stakeholders to chart the future roadmap for the gold-loan sector and unlock the potential of gold as a financial asset.
The summit aims to strengthen the operational capabilities of gold-loan companies, equipping them to scale efficiently and responsibly. Core discussions will address shared industry challenges while emphasizing corporate governance, regulatory compliance, and sustainable business practices.
Bringing together prominent voices from across the financial ecosystem, the event will examine the evolving role of gold in modern finance, emerging market opportunities, and strategies to expand credit access to underserved populations.
Key areas of deliberation include:
- Policy and regulatory developments
- Responsible lending and consumer protection
- Corporate governance and transparency
- Technological advancements and sustainable growth
Prominent industry leaders scheduled to participate include George Alexander Muthoot, Executive Vice-Chairman of Muthoot Finance; Thomas John Muthoot, Chairman and Managing Director of Muthoot FinCorp; and V.P. Nandakumar, Chairman and Managing Director of Manappuram Finance.

-
 International News2 hours ago
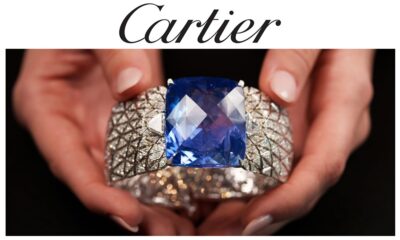
Cartier Romanov sapphire bracelet nets $4.9mn at Sotheby’s Geneva auction
-
 National News3 hours ago
FGLOC to host inaugural Gold Summit in Kochi
-
 National News6 hours ago
Domestic precious metal markets record steady retail pricing
-
 National News5 hours ago
GJEPC’s IIJS Bharat Signature 2027 Roadshow Connects with 40+ Jewellery Buyers in Sharjah